Sold house, land, shares or mutual funds? Know 9 reinvestment options to claim capital gains tax exemption
 1 hour ago
1
Related


RIGHT SIDEBAR TOP AD
Popular

CBSE Class 10, 12 Supplementary Results 2024: Marks verifica...
2 years ago
2084

NEET PG admit card 2024: NBEMS to release hall tickets today...
2 years ago
1889
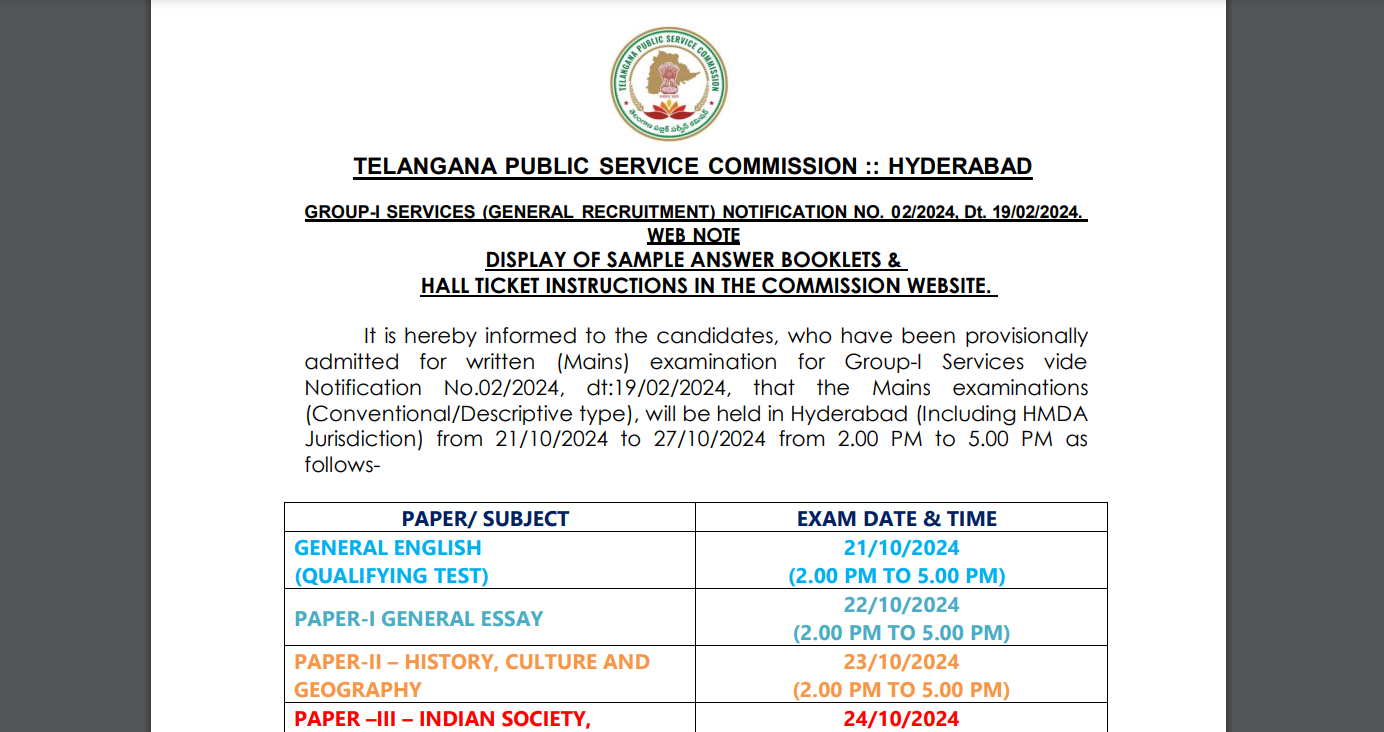
TSPSC Group 1 Mains exam schedule announced, exam timings re...
2 years ago
1805

Amazon Great Freedom Festival Sale 2024 coming soon: Get rea...
2 years ago
1493

iPhone 15, iPhone 15 Plus get massive discounts ahead of iPh...
2 years ago
1421
RIGHT SIDEBAR BOTTOM AD
 English (US) ·
© TelegramMagazine 2026. All rights are reserved