Got a stipend while studying? ₹18.34 lakh ITAT case explains when students can claim income-tax exemption
 1 month ago
14
Related

Income tax return filing: Why Nov 21 is an important date – ...
15 minutes ago
0

Can you be downgraded from business class despite paying ful...
24 minutes ago
0

Equity mutual funds amid market correction 2026: Should you ...
52 minutes ago
1
RIGHT SIDEBAR TOP AD
Popular

CBSE Class 10, 12 Supplementary Results 2024: Marks verifica...
2 years ago
2116

NEET PG admit card 2024: NBEMS to release hall tickets today...
2 years ago
1924
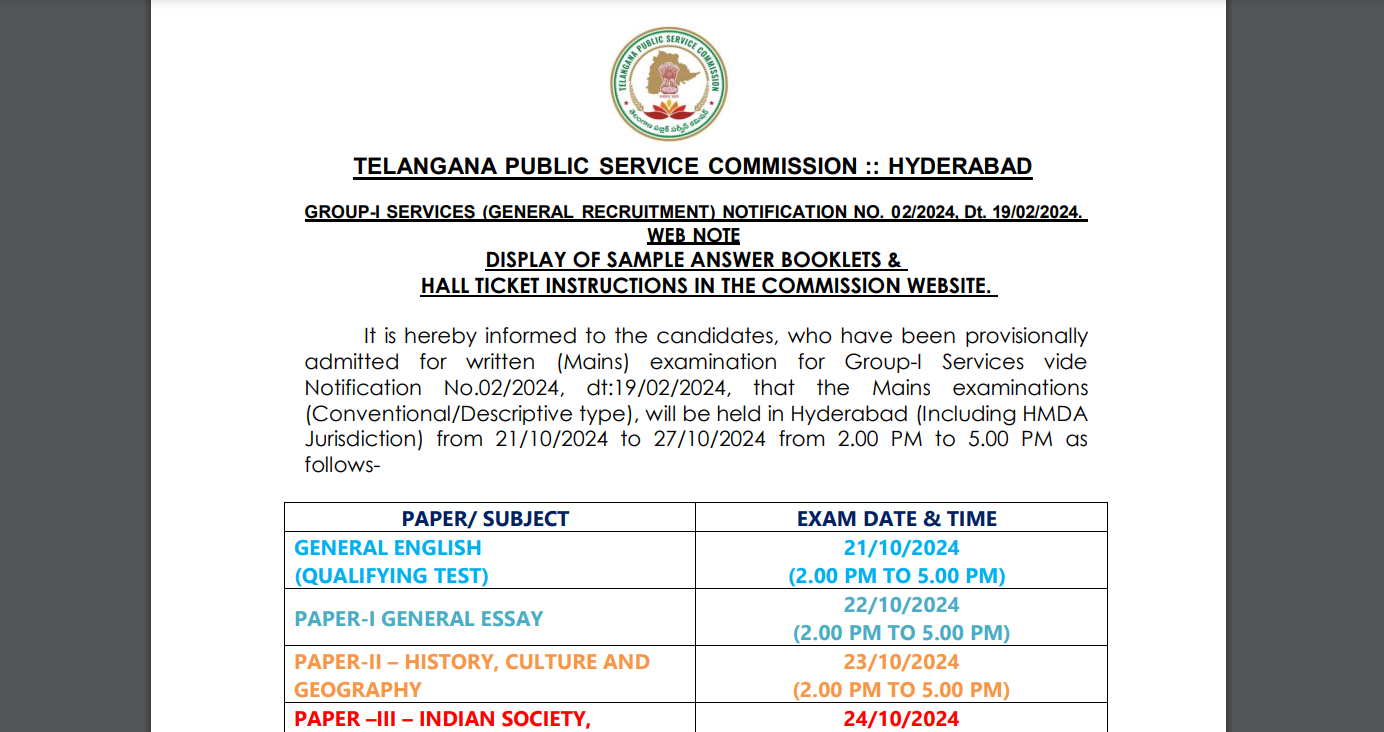
TSPSC Group 1 Mains exam schedule announced, exam timings re...
2 years ago
1853

Amazon Great Freedom Festival Sale 2024 coming soon: Get rea...
2 years ago
1522

iPhone 15, iPhone 15 Plus get massive discounts ahead of iPh...
2 years ago
1450
RIGHT SIDEBAR BOTTOM AD
 English (US) ·
© TelegramMagazine 2026. All rights are reserved